Your Local Mortgage Lender
Located in Birmingham, Alabama
Personalized Mortgage Experience
Jason Cook offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Birmingham, Alabama.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
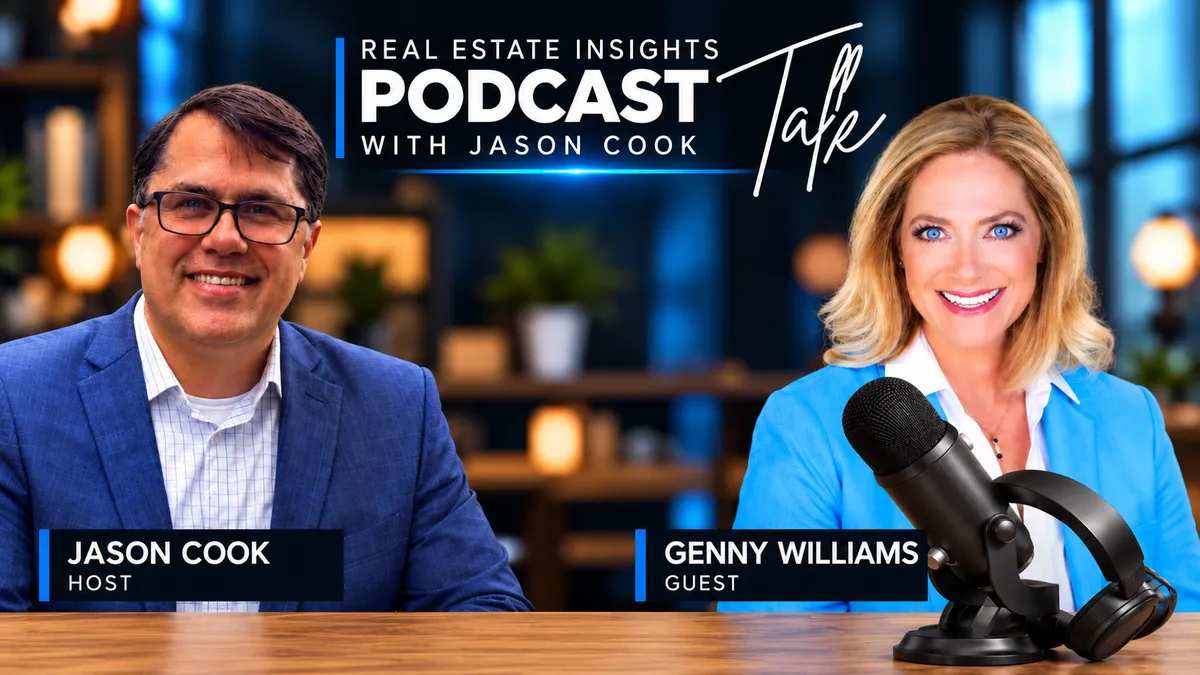
Real Estate Insights Podcast: Jason Cook Talks Birmingham Market Pricing and Dark Side Stories With Genny Williams
The Mississippi Girl Who Kicked and Screamed Her Way Into Real Estate and Never Left
Jason Cook launched the Real Estate Insights Podcast with someone he describes as a longtime friend, sometimes business partner, mentor, and real estate guru. Genny Williams has been selling real estate for twenty-nine years in the Birmingham area and brings a perspective on the market that only comes from having seen multiple cycles, sold haunted houses, and ordered an appraisal out of her own pocket before walking away from a listing that did not feel right.
She came to real estate pregnant, having walked away from a marketing position in the casino industry, needing health insurance, and running out of options she liked better. Her father had been a real estate broker her entire life. She resisted. The family vacations were punctuated by one more house to show. He was always on the phone. She knew what the life looked like and did not want it.
She went through the courses anyway and has been in it ever since.
The Anti-Salesperson Who Became an Expert Educator
From the beginning Genny’s philosophy was to educate rather than sell. She was going to be the agent who gave people enough information to make their own decisions without ever feeling pressured. Twenty-nine years later the philosophy has not changed but the clients have. The people she works with now have been through the process multiple times. The education shifts from explaining how transactions work to updating clients on how the market works right now compared to the last time they were in it.
That distinction matters enormously. The client who sold in 2020 when homes moved in days with multiple offers over asking has a mental model of real estate that no longer reflects what is happening. Genny respects the experience they bring while gently redirecting them toward the data that describes the market they are actually in.
The Pre-Listing Story That Shows What She Does Differently
Genny’s husband Jay is a licensed home builder. When she takes a listing they go through the property together looking for the things that will surface on a home inspection and cost the seller money in negotiations. The goal is to address those issues before the house goes on the market so they do not become negotiating leverage for buyers or reasons for deals to fall apart.
She gives a specific example from a listing at Villages of Holland Lakes. There was rotted wood around some windows that would have alarmed any buyer who noticed it and any inspector who found it. A buyer would have seen lack of maintenance and either asked for thousands in concessions or walked. The actual fix cost around three hundred dollars.
She tells a longer cautionary story about sellers who received her pre-listing punch list, did not want to address most of it, made a few cosmetic repairs with the wrong materials, and then had a buyer back out when the inspection found everything that had been on the original list. They spent thirty-something thousand dollars fixing the house, relisted it at a higher price, and had the remaining items surface on the next inspection requiring another twelve thousand. Jay’s saying is that you are either going to pay for it now or pay for it later, and when you pay for it later it always costs more.
The Listing She Walked Away From
Genny has enough market knowledge to recognize when something feels off even when the quick data seems to support the seller’s expectation. She was working with clients who wanted 1.4 million. The data suggested it might be possible. Something in her gut was not comfortable with it.
She ordered an appraisal at her own expense. The house turned out to be three hundred to three hundred and fifty square feet smaller than what the owners were told when they originally purchased it. The numbers changed drastically. She declined to take the listing because she did not believe she could ever meet their expectations and a frustrating experience that damaged the relationship was not something she was willing to create.
Sometimes you walk away. She knows when.
What She Tells Buyers Right Now
In October 2026 Genny is telling buyers to get the expectation of rates coming back down out of their heads. She feels strongly that rates may go higher before the end of the year given ongoing inflation pressure. She has been working with one buyer since February who has made offers and backed out repeatedly while watching rates move upward. That buyer ended up closing around seven percent. The message Genny has been giving throughout is that this is the new norm and waiting for something better is costing real money in the form of higher rates and higher prices as time passes.
Her solution for buyers dealing with affordability is a conversation with a lender like Jason Cook about what can be done with the rate. Asking the seller to cover not just closing costs but also a rate buydown is the kind of strategy she brings up in the first post-qualification conversation. Understanding what tools exist changes the calculation for buyers who assume the payment they were quoted is the payment they are stuck with.
What She Tells Sellers Right Now
October has been quiet for three consecutive years and Genny sets that expectation with every seller before the month arrives rather than letting the silence be a surprise. The last rate increase did not help and buyer activity naturally compresses around fall schedules and holidays.
She is also direct about something counterintuitive. A price reduction in the current market may not move the needle. In a highly desirable location with multiple offers a price adjustment creates activity. In a market where buyers have more choices and are taking longer to decide the price reduction without a corresponding quality and condition advantage may not produce a meaningful change in showing activity.
Her approach is to communicate daily with sellers, run her marketing consistently, and stay visible so clients know the work is happening even when the market is quiet. Agents who go into hiding during slow periods leave sellers feeling abandoned and questioning why they are paying a commission to someone they cannot reach.
She also notes the trap of watching competitive price reductions in the neighborhood. A seller who drops below everyone else may find all the competing listings drop below them the following week. Reading the neighborhood data before deciding on a price adjustment is part of how she manages that situation.
The Dark Side of Real Estate and the Dirty Deeds Podcast
Genny runs a second podcast called Dirty Deeds that does not help her sell houses and she is clear about that. It tells the stories of the dark things that happen in real estate that nobody talks about publicly. Haunted houses. Properties where suicides, murders, and other traumatic events had occurred. She says if it was a dark history property she was the agent people called. Every episode looks for the light in the darkness and she frames it with a faith perspective throughout.
She also runs a YouTube channel called Get a Real Estate Life that she originally built around coaching and consulting before returning to active sales. Her video promotion for listings runs through a UK-based team and a local videographer in Alabaster. TikTok and Facebook Reels are active channels. The listing promotion infrastructure she has built is meaningfully more substantial than most Birmingham agents are running.
The Pricing Philosophy That Has Not Changed in Twenty-Nine Years
The buyer determines what the house is worth. Not the seller, not Zillow, not Redfin, not an AI query that returns a range based on surface-level data. A buyer is going to walk in and make the final determination about what they will pay and nothing the listing agent does changes that fundamental reality. The job is to position the property so the right buyer assigns the right value and to eliminate the friction that prevents that buyer from getting comfortable enough to close.
Every house sells in every market. It all comes down to price. Genny has sold houses at eight and nine percent. The market always moves inventory when the price is right. The question is finding that price before it costs the seller the market time and negotiating position that come with overpricing.
How to Find Genny Williams
Find her on Facebook and TikTok as Genny Williams with a G-E-N-N-Y spelling. Find the listing promotion work and market content on YouTube at Get a Real Estate Life. The Dirty Deeds podcast is available on Facebook and TikTok for anyone who wants the spooky side of twenty-nine years in Alabama real estate.
Jason Cook hosts the Real Estate Insights Podcast and is available for mortgage financing conversations across the Birmingham area. Reach out to Jason Cook to connect on the lending side of any transaction Genny is working and to run the numbers on what rate buydown strategies and seller concession structures could do for buyers navigating the current market.
Sources
AlabamaAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
